

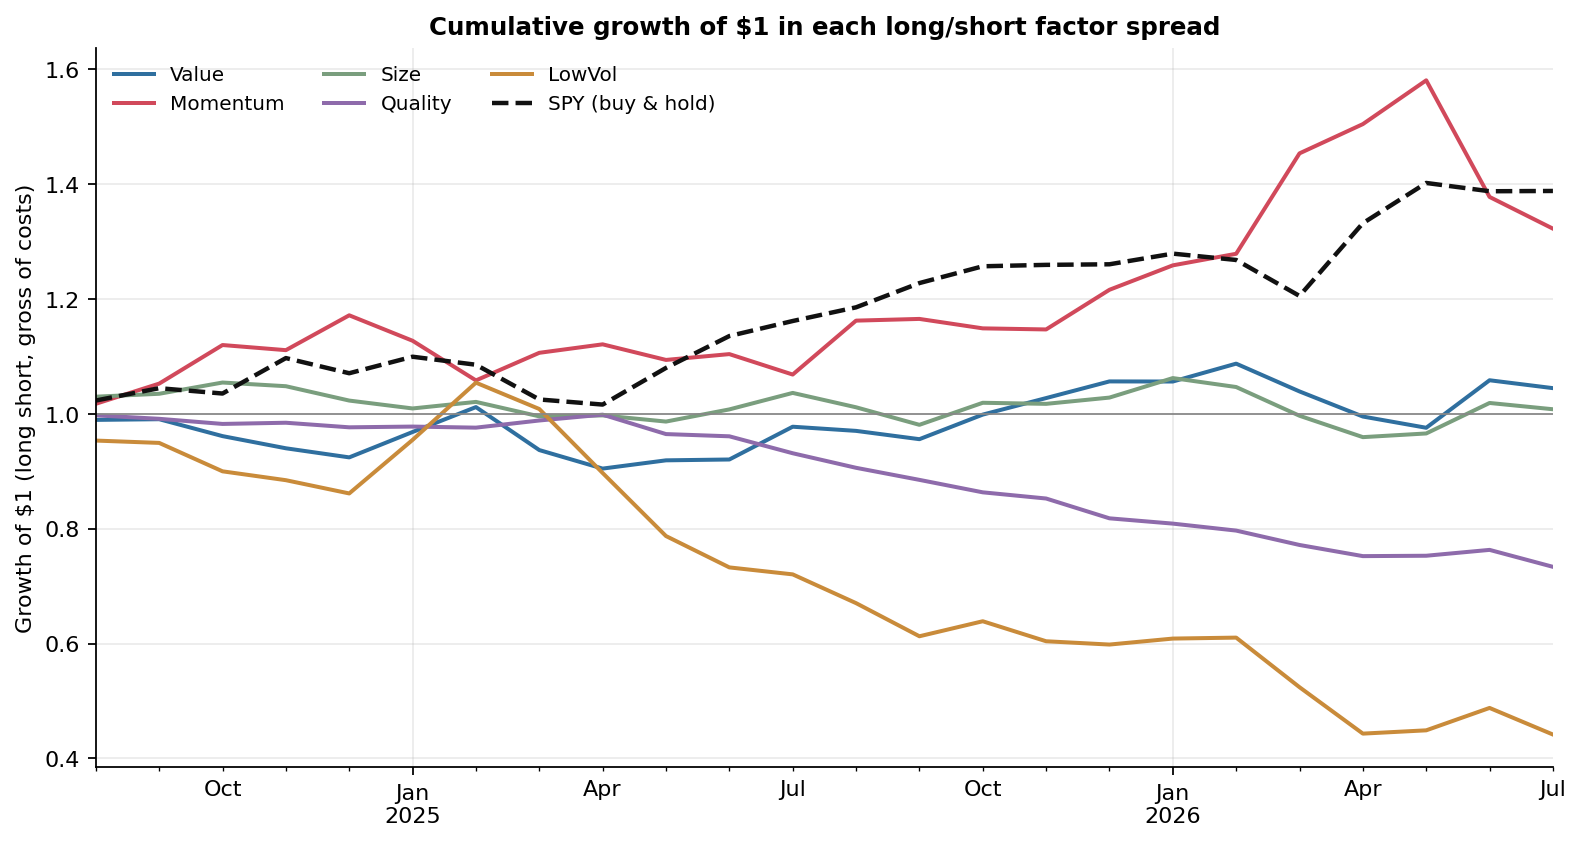
This paper discusses three classical kinds of quantitative trading: the high-frequency trading, arbitrage, and factor investing. It then the tests five well-known stock factors on the S&P 500 over 24 months, from August 2024 to August 2026. Only momentum clearly made money, gaining 16.9% a year with a Sharpe ratio of 0.84. Value gained 3.1% and size 0.8%, which is close to nothing given how much both swung. The quality lost 14.2% and low volatility lost 31.4%. The market explains much of this. It was a strong bull market, but a narrow one, and the wildest stocks rose 48% a year while the calmest rose only 6.5%. Sorting stocks inside their own industry lifts value to 12.0% and size to 8.4%, so the plain sorts were partly bets on industries. Two years is a short test. These results mostly show how easily a short window can hide a long-run pattern.